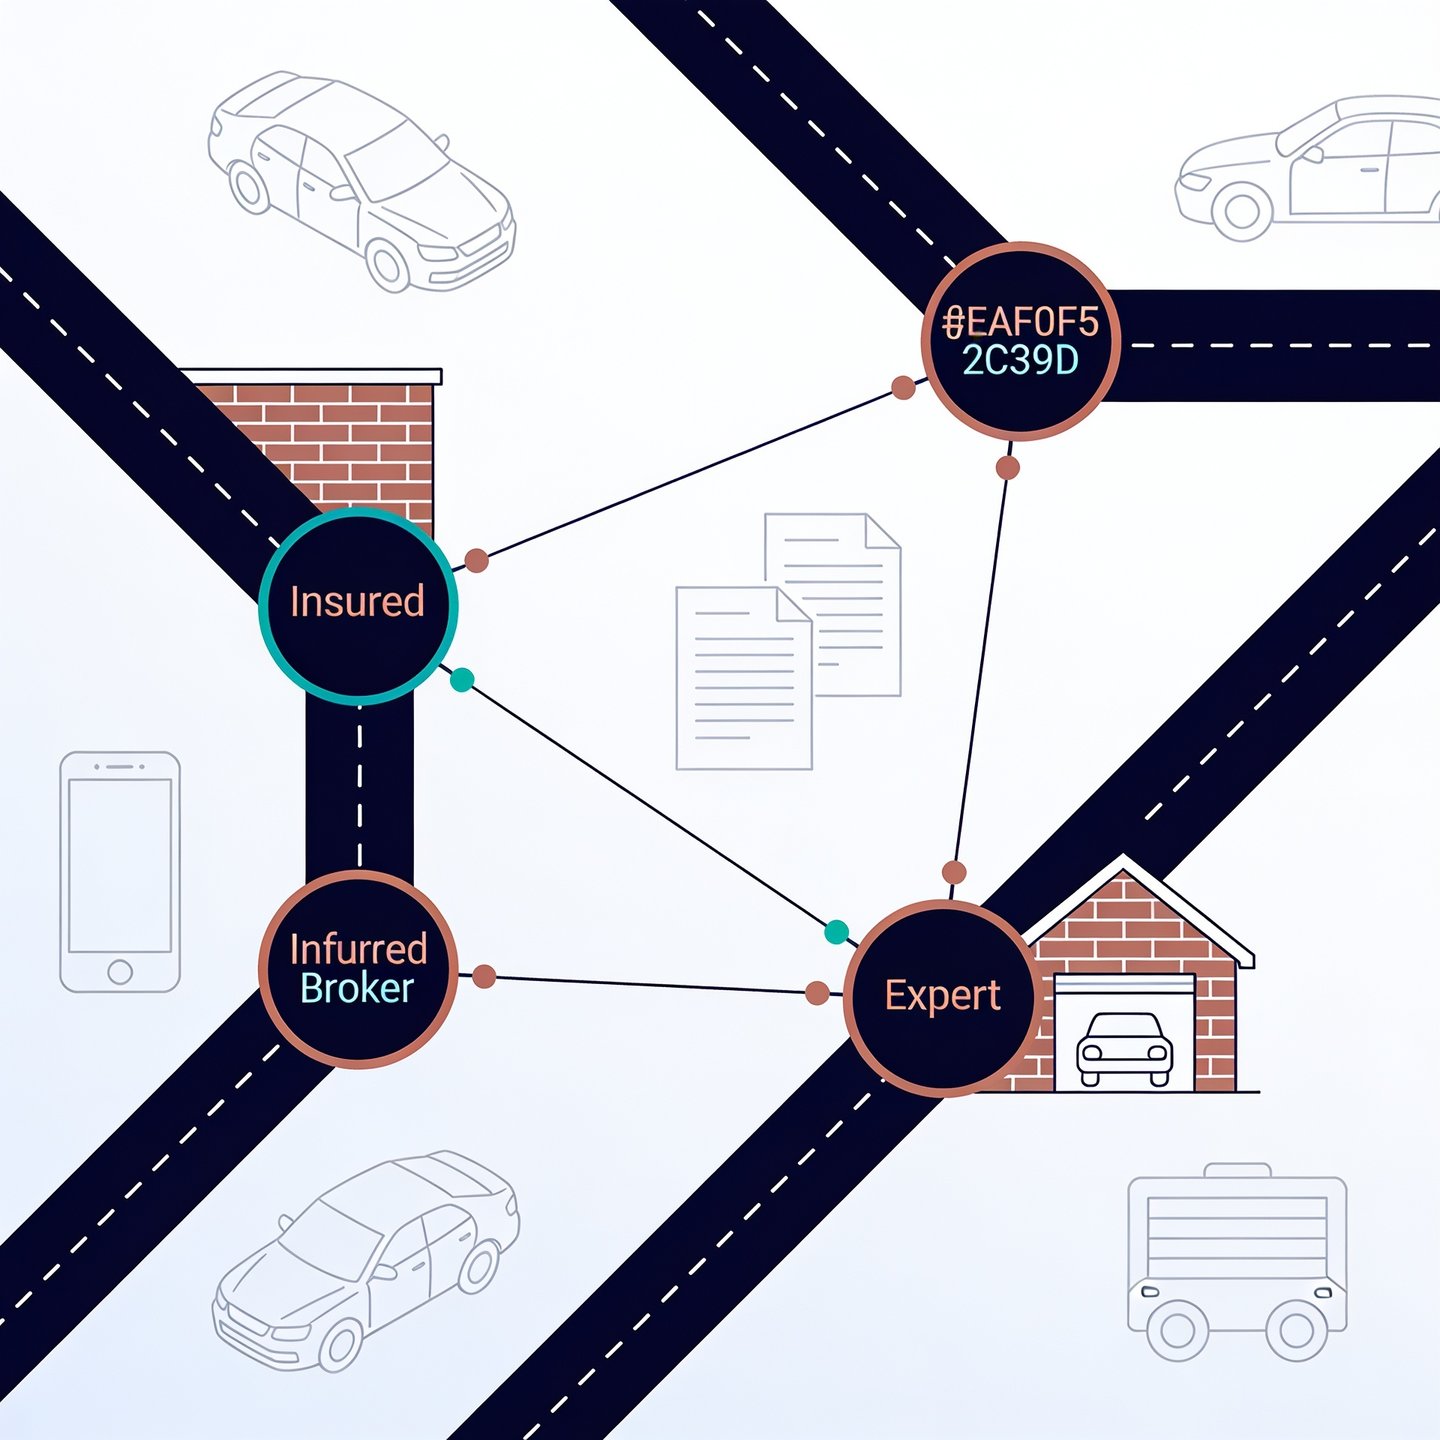
Auto claims management in francophone West Africa sits at the intersection of a strict regulatory calendar and a largely paper-based operating reality. Insurers must meet indemnification deadlines set by the CIMA Code while their claims files still travel by hand between insured, garage, expert and broker. Closing that gap is what digitalization is now being asked to do.
For insurance professionals in Nigeria and Ghana, the CIMA zone is worth understanding on its own terms. It is a distinct regulatory bloc of 14 member states, including Côte d'Ivoire, Senegal, Cameroon, Benin and Mali, according to commentary on the 2023 CIMA Code reform (TABOO Conseil). The operational pressures, however, are familiar to any auto claims team on the continent: incomplete files, slow garage-to-insurer communication, and a documentation gap that fraud can exploit.
What is the regulatory path of an auto claim in the CIMA zone, from accident report to indemnification?
A standard CIMA-zone auto claim opens with a constat amiable, the joint accident report filled in by both drivers, according to a breakdown of the CIMA claims journey by ORIS. Where the two parties disagree, or where the accident involves bodily injury, a police or gendarmerie report (PV) is used instead. The file is then built around photos of the damage and the two insurers' reference numbers, before moving to the insurer for assessment and, where needed, an independent expert's report.
Why this matters for cross-border comparison
The sequence is not radically different from claims handling in Nigeria or Ghana. What differs is the regulatory backstop: CIMA sets statutory deadlines for the insurer's response, and those deadlines carry financial penalties, which changes how much slack a claims department can tolerate in its paper trail.
What deadlines does the CIMA Code impose on insurers for offer and settlement, and what's at risk from delays?
A 2021 reform, in force since 1 August 2023, tightened the indemnification calendar significantly. According to commentary on regulation n°0004/CIMA/PCMA/PCE/2021 amending article 231 of the CIMA Code (TABOO Conseil), the deadline for an insurer to present an indemnity offer fell from 12 to 6 months from the accident for bodily injury claims, and from 8 to 6 months from the date of death for fatal accidents.
The cost of missing a deadline
Article 233 of the CIMA Code provides that a late indemnity offer accrues interest at 5% per month of delay, cumulative, according to the same commentary. That is a meaningful financial exposure on a portfolio basis, and it turns claims-cycle time from an operational metric into a direct line-item cost. It is worth verifying the exact wording of articles 231 and 233 against the official CIMA Code text before applying these figures to a specific file, since the commentary cited here is a secondary legal analysis rather than the primary regulation.
Why does claims management remain slow and costly for insurers and brokers in francophone West Africa?
The region's insurance market is still comparatively small and underpenetrated. West Africa generated 3.91 billion USD in premiums in 2024, or 5.3% of the 73.6 billion USD African total, with penetration around 0.7%, according to Atlas Magazine. Southern Africa, by contrast, accounted for over 72% of the continent's premium volume in the same year. Thinner margins make claims leakage proportionally more damaging to insurers operating at this scale.
| Country | 2024 premium volume (Atlas Magazine) |
|---|---|
| Côte d'Ivoire | 998.6M USD (574.5M USD non-life) |
| Senegal | 472M USD |
| Cameroon | 457.3M USD |
| Benin | 164M USD |
| Mali | 113.3M USD |
On individual files, the constraint is rarely bad faith on the insurer's side. According to ORIS, for straightforward material-damage claims in the CIMA zone, it is file completeness, missing documents, unreturned garage quotes, delayed expert sign-off, that separates a six-week settlement from a six-month one. This qualitative observation should be treated as illustrative rather than as a verified regional benchmark, but it matches what claims teams describe in practice: the bottleneck is coordination between four parties, not the regulation itself.
How does digitalization cut delays and fraud in auto claims management in francophone West Africa?
Digital claims platforms address the coordination problem directly by putting the insured, broker or insurer, expert and garage on the same real-time file. Declaration by app, web portal or WhatsApp removes the first point of friction, since the insured no longer depends on physical access to a branch to open a file. From there, the garage submits quotes and invoices digitally, the expert validates remotely, and the file moves to settlement as soon as it is complete.
Certified photos as a fraud control
Documentary fraud, inflated or fictitious garage quotes and invoices, is a structural risk in any market where claims files rely on paper documents and manual photo submission. Certified capture technology, such as guided photo capture with geolocation and timestamp, closes much of that gap by making it harder to submit a photo that was not taken at the right place and time. Côte d'Ivoire's move to digitalize vehicle insurance attestations was explicitly framed as a way to curb fraud tied to the production and reproduction of paper documents, according to Le360 Afrique, though that initiative targets insurance certificates rather than the claims file itself, so it should not be read as a direct measure of claims fraud. For broader context, auto insurance fraud detected in France rose 26% between 2022 and 2023 to nearly 237 million euros, according to Ouest-France; this is a European data point cited only as an illustration of how quickly documentary fraud can scale when photo and invoice controls are weak, not a CIMA-zone statistic.
Our practical guide to auto insurance claims management software in Africa goes deeper into how these building blocks, mobile declaration, remote expertise, certified photos, fit together across markets on the continent.
What role does the ECOWAS Brown Card play in cross-border claims, and how does a digital platform handle it?
Many auto claims in West Africa involve vehicles registered in a neighboring country. The ECOWAS Brown Card, established by protocol A/P1/5/82 signed in 1982, guarantees that a victim of an accident caused by a foreign vehicle circulating within the ECOWAS zone is indemnified in their own country through the national bureau, with the council of bureaux based in Lomé, according to ORIS. This mechanism matters for claims teams because it adds a cross-border verification step: confirming the foreign vehicle's Brown Card coverage and routing the claim through the correct national bureau.
A digital claims platform that already tracks insurer references, expert reports and garage documents in one file can extend the same logic to a Brown Card claim, attaching the cross-border reference and correspondent bureau details to the file rather than managing them on a separate paper track. This reduces the risk that a cross-border claim simply stalls for lack of a single owner following it up.
What concrete results can an insurer or broker expect from digitalizing auto claims in this zone?
Platforms built specifically for African auto claims are already operating at meaningful scale. YourSmartFlow, for instance, reports more than 250,000 auto claims optimized in 2025 across more than 50 insurer and broker clients in five African countries, with go-live typically achieved within four weeks. The company estimates a 10 to 15% reduction in claims burden for clients, with first-year return on investment, and its settlement workflow can trigger automatically via API once a claims file is complete, certified photos, expert validation and garage documents included.
These figures describe the platform's own client base rather than a CIMA-zone-wide benchmark, and insurers evaluating any digital claims tool should ask for country-specific reference data before committing to a rollout. What they do illustrate is the direction of travel: shortening the path from accident report to settlement is now a software problem as much as a regulatory one.
Conclusion
CIMA's tightened deadlines and interest penalties raise the cost of a slow claims file, while the underlying friction, paper documents moving between four parties, remains the main reason files take six months instead of six weeks. Digitalizing declaration, expert validation and garage documentation does not change the regulation, but it removes most of the delay that the regulation was designed to penalize. For claims and ops leaders comparing notes across Nigeria, Ghana and the CIMA zone, that is the practical lesson: the tool matters less than closing the four-party gap it is built to solve.
Frequently asked questions
What is the legal deadline to declare an auto claim in the CIMA zone, and what happens if the insured is late?
The CIMA Code process typically starts with a constat amiable or, where there is disagreement or bodily injury, a police or gendarmerie report, according to ORIS's breakdown of the CIMA claims journey. The specific declaration deadline and consequences of a late declaration should be checked against the current CIMA Code text, since the research reviewed here focused mainly on the insurer's indemnification deadlines rather than the insured's declaration window. In practice, insurers in the zone generally expect prompt declaration to avoid disputing coverage later.
Is the constat amiable mandatory, or can a police report (PV) replace it in the CIMA zone?
The constat amiable, filled in jointly by both drivers, is the standard starting document for a CIMA-zone auto claim, according to ORIS. A police or gendarmerie PV is used instead when the drivers disagree or when the accident involves bodily injury. Both documents serve the same purpose: establishing the facts of the accident before the file moves to assessment.
What exactly does the CIMA Code say about indemnification deadlines, and are they actually respected in practice?
Since the 2023 reform of article 231, insurers must present an indemnity offer within 6 months of the accident for bodily injury claims and within 6 months of the date of death for fatal accidents, according to commentary on regulation n°0004/CIMA/PCMA/PCE/2021. Article 233 backs this with a cumulative 5% monthly interest penalty for late offers. Whether these deadlines are consistently met varies by insurer and by file completeness, and no CIMA-zone-wide compliance statistic was found in the sources reviewed, so this should be verified against national insurance directorate or FANAF data before quoting a specific compliance rate.
How does a cross-border claim work under the ECOWAS Brown Card when the at-fault vehicle is from another CIMA or ECOWAS country?
The ECOWAS Brown Card, created under the 1982 protocol A/P1/5/82, allows a victim to be indemnified in their own country through the national bureau, even when the at-fault vehicle is registered abroad, according to ORIS. The claim is routed through the correspondent national bureau, with the overall council of bureaux based in Lomé. This avoids requiring the victim to pursue a claim directly in the foreign vehicle's home country.
How does digitalization, certified photos, remote expertise, WhatsApp declaration, reduce fraud on garage quotes and invoices?
Guided photo capture with geolocation and timestamp makes it harder to submit a quote or invoice photo that was not taken at the claimed location and time, closing a common documentary fraud route. Remote expert validation adds a second check before a quote is approved for settlement. Côte d'Ivoire's digitalization of vehicle insurance attestations was explicitly aimed at reducing paper-document fraud, according to Le360 Afrique, though that example concerns insurance certificates rather than claims files specifically.
What concrete gains in delay, cost or fraud can an insurer or broker expect from digitalizing auto claims management in this zone?
Platforms operating across African markets, such as YourSmartFlow, report an estimated 10 to 15% reduction in claims burden and first-year ROI for insurer and broker clients, based on more than 250,000 optimized claims in 2025 across 50-plus clients in five countries. These figures reflect a specific platform's client base rather than an independent CIMA-zone benchmark. Insurers should ask any vendor for country-specific reference data before extrapolating these results to their own portfolio.